 Malaysia
The semiconductor industry highlights the benefits and complexities for Malaysia as it navigates its trade relationship with China, balancing economic gains against the risks of dependency.
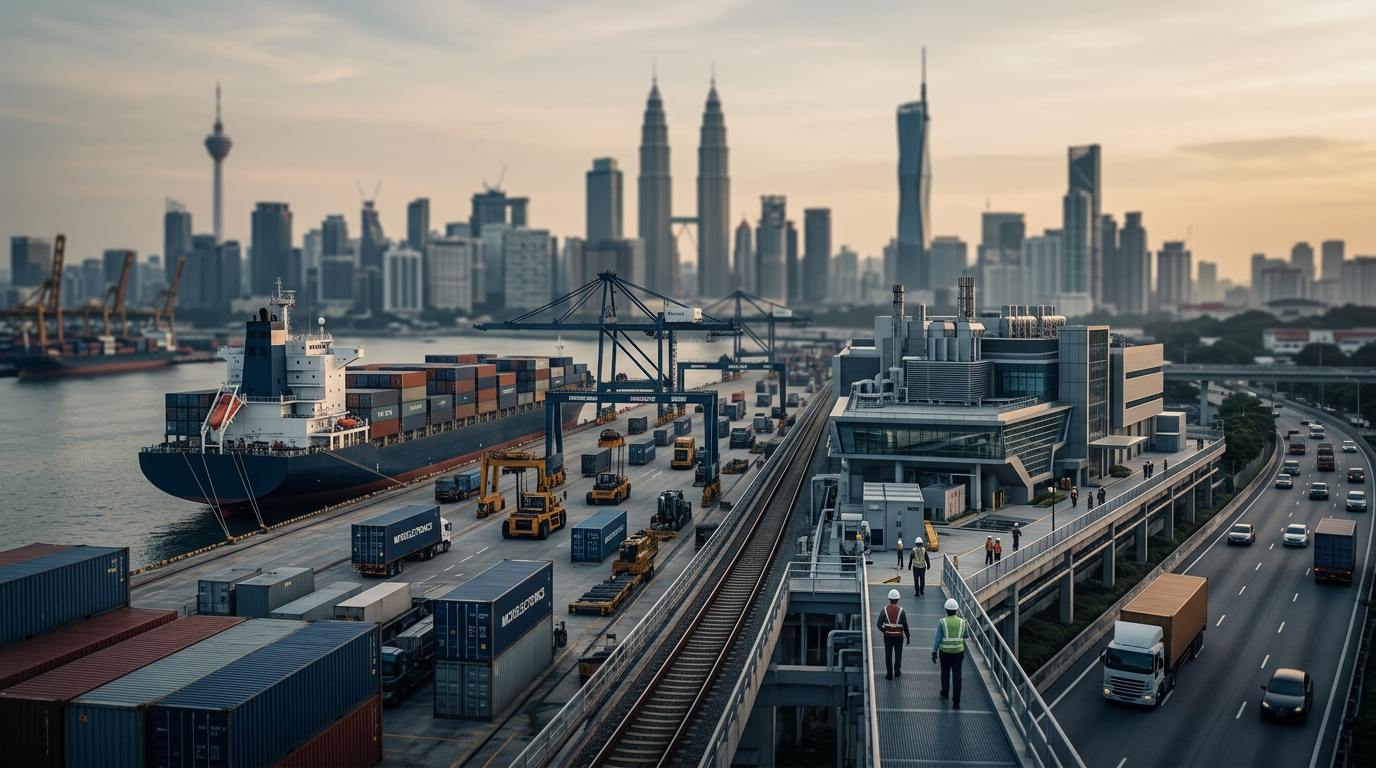
An September report from The Star highlighted the role of semiconductor shipments in sustaining Malaysia's export momentum. This news puts a spotlight on a critical sector not just for Malaysia, but for the wider region, and illustrates the complex trade-offs ASEAN nations face, particularly in their relationship with China.
Institutions and Infrastructure
Malaysia's long-term investment in the electronics and electrical (E&E) sector, especially in outsourced semiconductor assembly and test (OSAT), has built a durable base. The nation has established industrial parks, a skilled workforce, and logistical networks that make it an attractive node in the global semiconductor supply chain. This physical and institutional infrastructure is a core asset. As global firms look to diversify their supply chains, Malaysia's established capabilities give it an advantage. The government's continued support through agencies like the Malaysian Investment Development Authority (MIDA) reinforces this, providing a stable framework for foreign and domestic capital. However, the concentration of this industry in specific economic zones also presents challenges, requiring constant upgrades to infrastructure like ports and power grids to keep pace with technological demands.
Capital and Dependency
The flow of capital into Malaysia's semiconductor sector is a double-edged sword. While it fuels growth and job creation, a significant portion of this investment, and the ultimate demand for these components, is linked to China's vast electronics manufacturing ecosystem. As noted in "ASEAN Rising", this type of economic integration illustrates how "trade depth with China is now a structural feature, not a cyclical one." For Malaysia, this means that its export performance is increasingly tied to the health of China's industrial sector and its access to that market. Managing this dependency is a primary task for policymakers. The challenge is to leverage Chinese capital and demand without becoming overly exposed to shifts in Beijing's industrial policy or geopolitical tensions that could disrupt these trade flows.
Talent and Trust
Sustaining the semiconductor industry's growth requires a pipeline of high-skilled talent. Malaysia has a creditable record of producing engineers and technicians, but the demand is intensifying. The country must continue to invest in its universities and vocational training centers to develop the human capital needed for more advanced manufacturing and design activities. Building this talent pool is a matter of national industrial strategy. Furthermore, the global semiconductor industry operates on a foundation of trust. For Malaysia, maintaining its reputation as a reliable and neutral location for manufacturing is paramount. This involves navigating the technological rivalry between the United States and China carefully. By assuring international partners of its stability, intellectual property protection, and consistent policies, Malaysia can build the trust necessary to attract further investment and move up the value chain.
What to watch
Observe how Malaysia balances its efforts to attract a wider range of international investment in high-value semiconductor activities, such as wafer fabrication and integrated circuit design, against the persistent gravitational pull of China's market. The policy choices made regarding foreign investment, technology partnerships, and talent development will indicate the country's long-term strategy for managing its position within the global technology race and its deep economic ties with China.
 Vietnam
 Philippines